ALAM MO BA?
...na ang kakulangan sa Healthcare ang isang malaking rason kaya nalulubog sa utang ang isang pamilya?!
Unfortunately...
• nare-Realize lang ng karamihan na napaka-IMPORTANTE ng Healthcare kapag may sakit na, nasa hospital na, o nag-retire na.
• Medical costs double every 5 to 7 years.
• Maraming doctor at maraming gamot, pero bakit namamatay ang pasyente? Madalas, dahil WALANG PERANG pampagamot!
There are 3 Kinds of Healthcare
Short-term healthcare, Long-term healthcare, and Senior Care.
Short-term Healthcare
Ito ang healthcare na binabayaran taon-taon up to age 60 (magamit man natin o hindi).
Kapag nagpa-check up tayo o na-confine, sagot ng healthcare company ang bill natin. Kapag hindi natin nagamit, hindi carried over ang benefits the following year.
Kung empleyado ka, binabayaran ito ng kumpanya HABANG nagta-trabaho ka pa. Oras na mag-resign ka, o mag-retire na, hindi ka na covered.
Tanong: Kailan lumalabas ang mga mas seryosong sakit - habang bata, o kapag tumanda na tayo?
Senior Care
Ito naman ang yearly healthcare for Seniors age 60 pataas.
Since alam ng healthcare companies na madalas nang magkasakit ang mga Senior, ito ang pinakamahal na healthcare.
Long-term Healthcare
Ito ang healthcare na pwede nating simulan habang bata pa tayo, o habang hindi pa tayo Senior (10 to 60 years old).
Ito ang pinakamurang healthcare dahil pitong (7) taon lang nating huhulugan, pero covered tayo hanggang pagtanda.
Product Comparison
Alarming Health Realities...
- In 20 years, the elderly will outnumber the youth by a ratio 4:1
- Aging workforce is the biggest economic challenge over the next decades
- Heart disease is the number one cause of mortality in the Philippines
- Medical inflation hits nosebleed levels, 3-4 times economic inflation
- Cost of medicines in the Philippines is 600% higher than our neighboring Asian countries
- Health conditions in the Philippines remain among the poorest in East Asia
- More and more people die not because of no doctor or no medicine but because of money
Short Term Healthcare TRADITIONAL HMO |
Long Term Healthcare HEALTH SAVINGS ACCOUNT |
|---|---|
| Renewal not guaranteed if with high claims | Renewal is guaranteed |
| Yearly increase of premium | Fixed premiums for 7 years |
| Generally, no insurance coverage some provide insurance, but very low coverage |
With Four (4) Way Insurance Coverage up to the Long Term healthcare Plan:
|
| No accumulation of unused health fund | All unused health fund accumulates with interest |
| No return of premiums (ROP) for non-utilization | With returns of premiums up to the contract price for non-utilization during the paying period |
| Covers only up to age 60 | Covers beyond age 60 with long term care yields * |
| Pre-existing illness is not covered during the 1st year and lifetime / permanent exclusions may be issued on the 2nd year onwards | Pre-existing is not covered during accumulation period. No exclusions after the 7th year of coverage * |
| Inflexible, non-transferable benefit design | Flexible, transferable, and may be redated benefit design |
| Reinstallment is limited only within 30 days of lapsed policy | Reinstallment within 2 years of lapsed policy |
| Access to non-accredited physicians and medical network is not covered | Access to non-accredited physicians and medical network is covered after the 7th year |
| Out-patient medicines and cosmetic treatments not covered | Out-patient medicines and all illness including cosmetic and maternity are covered after the 7th year * |
| Continuous yearly payment terms | Seven (7) years or spot-cash payment options |
| Anxious, worrisome and insecure healthcare status after employment or during retirement years | No worries... |
Kaiser International Healthgroup, Inc. is an actuarially-sound, product-based business. It brings together the best features of an HMO, Health Savings Plan, and financial investment.
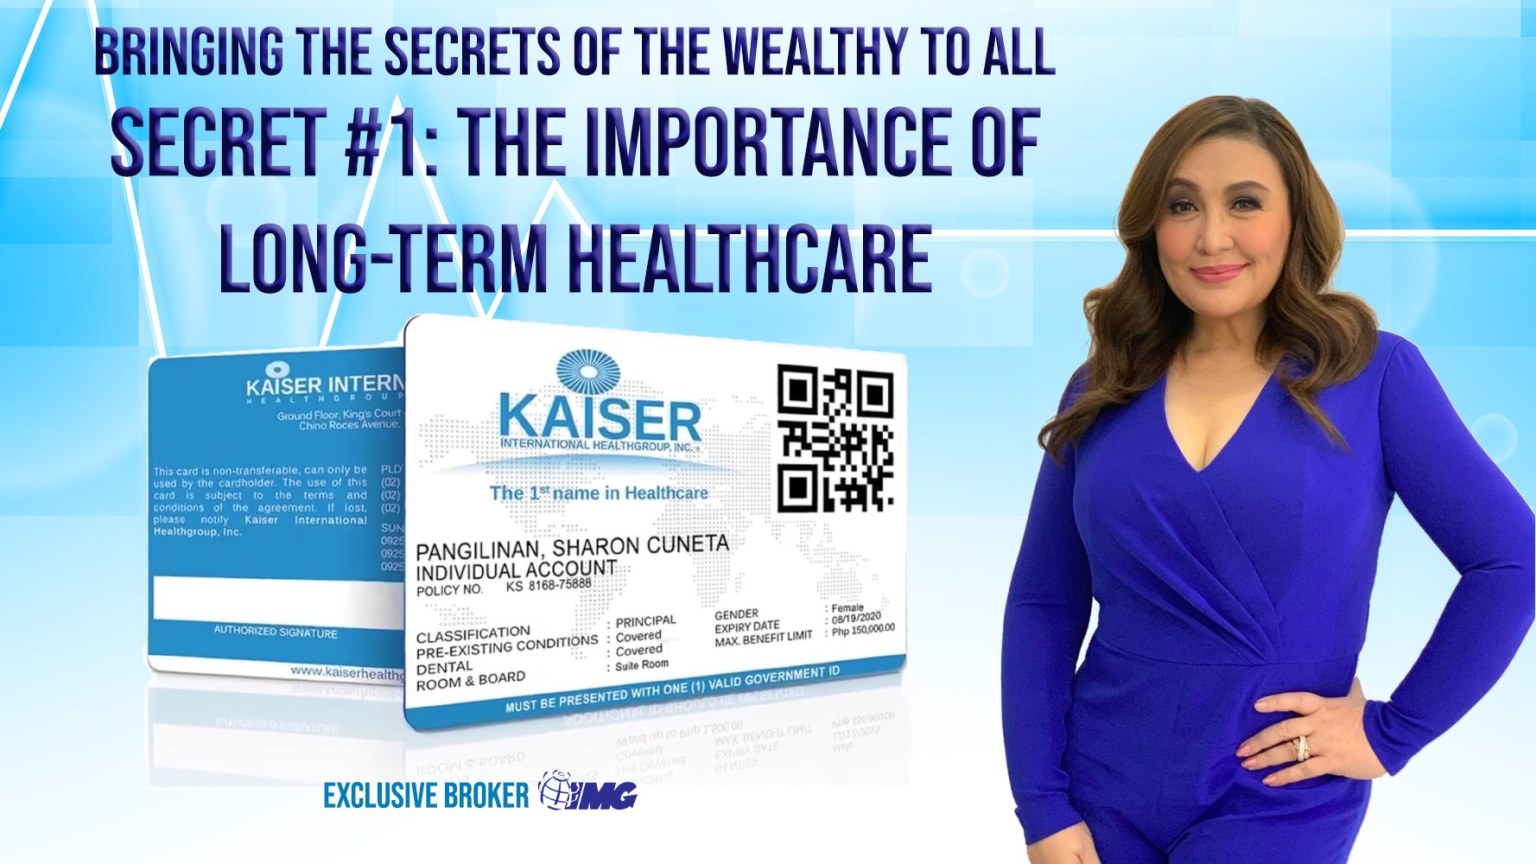
The KAISER Long-Term Healthcare is a 4-in-1 product.
Life Insurance
Covered tayo with Life and Accidental Insurance for 20 years, in case of untimely death.
In case the insured passes away during the paying period of 7 years:
1) The remaining installments will be waived.
2) The beneficiaries will receive the insurance proceeds.
3) At malilipat kay Beneficiary #1 ang policy. Siya na ang bagong owner of the plan. Wala na siyang babayaran. All investment and healthcare benefits, siya na ang makakagamit at makakakuha.
Healthcare
SHORT-TERM + LONG-TERM HEALTHCARE.
Kung magkasakit tayo NGAYON o pagdating ng ating SENIOR Citizenship, pwede nating gamitin ang Kaiser in all accredited clinics and hospitals nationwide.
Investment
Ito lang ang Healthcare Plan na nire-Reward tayo kung hindi tayo nagkakasakit. The Healthier we are, the Better because the More our INVESTMENT GROWS.
Once our plan matures at the end of 20th year, pwede natin i-withdraw, o iwanan lang ang pera para tuloy-tuloy lumago for our Long-term healthcare needs, or source of Retirement Fund (Passive Income).
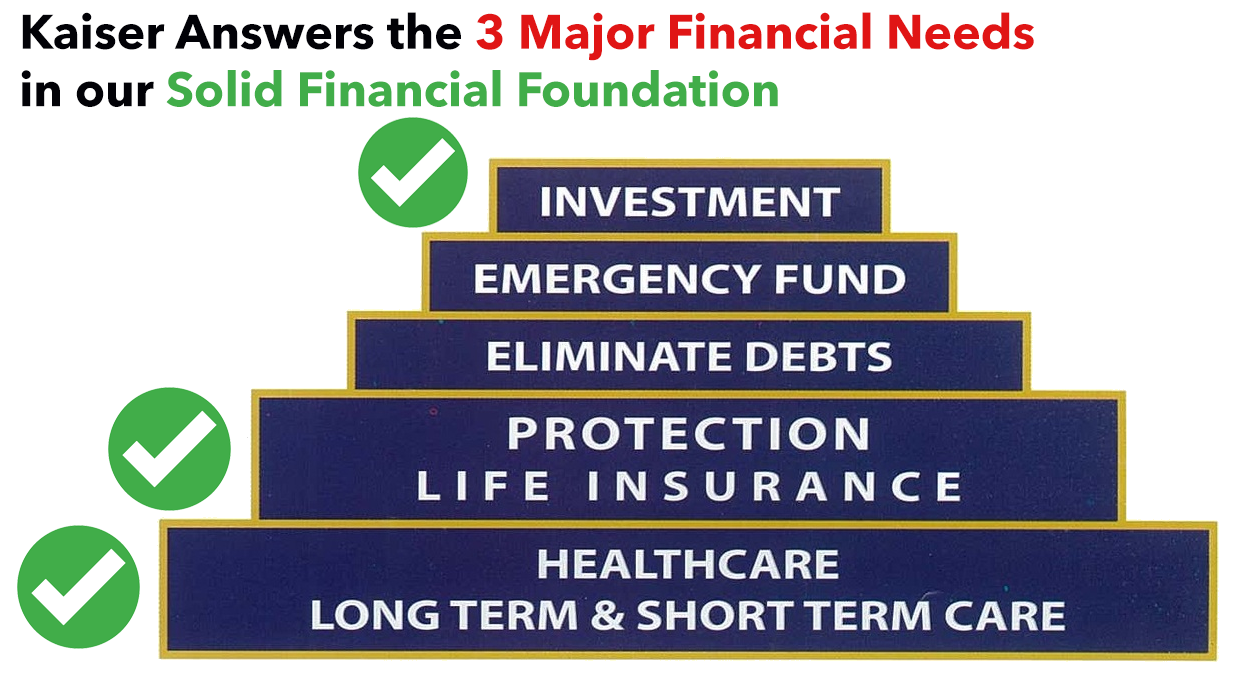
You can build a SOLID FINANCIAL FOUNDATION.
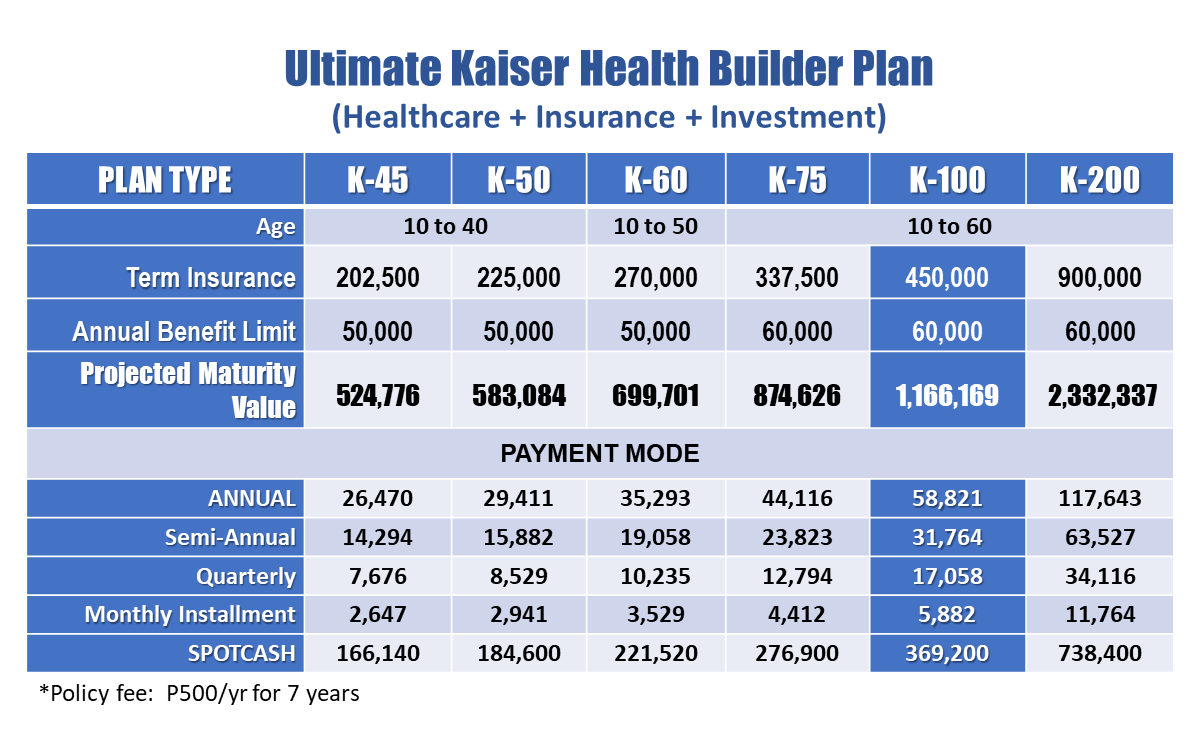
KAISER PRE-COMPUTED TABLE
HOW TO START YOUR KAISER SAVINGS PLAN?
OPTION # 1
Pwede ka mag-enroll ng Kaiser Saving Plan mo through Online Kaiser Application.
Click the link below for instructions.